A U.S. company pays you a $100 dividend. Your brokerage account shows only $70.
For a foreign investor seeing that for the first time, the obvious question is: where did the other $30 go?
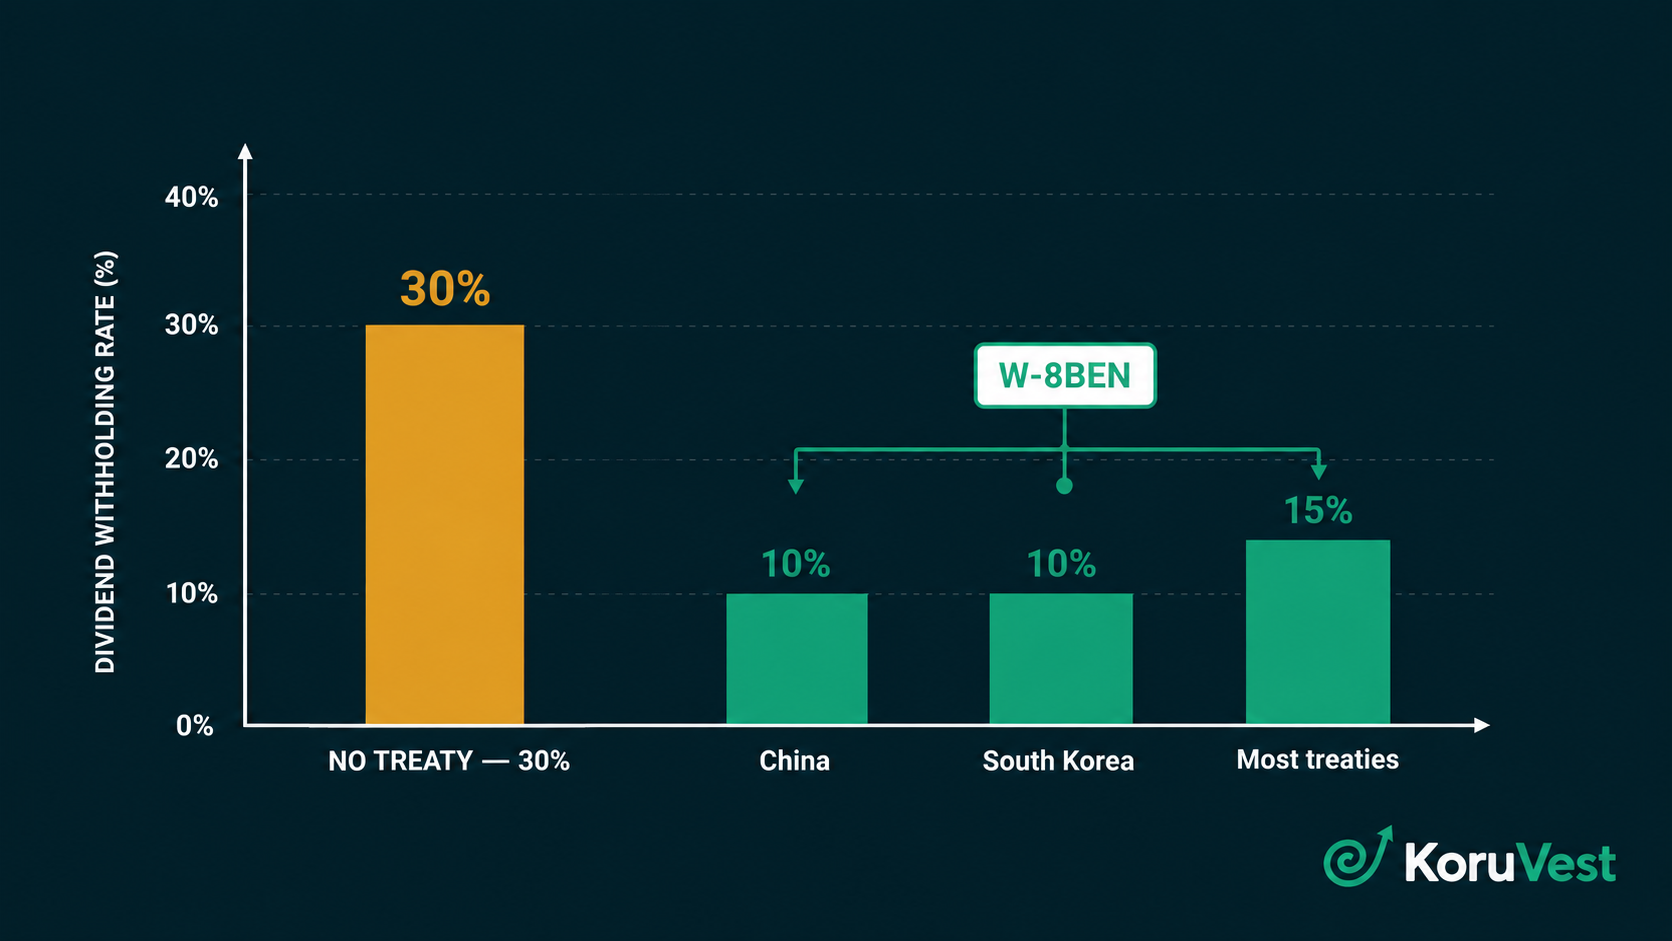
In many cases, the answer is U.S. withholding tax. U.S.-source dividends paid to a nonresident alien generally start with a 30% statutory withholding rate. But that 30% is only the starting point. If you are entitled to benefits under a U.S. income-tax treaty, the rate may be lower.
That is where Form W-8BEN comes in.
It is often described as the form that “cuts your U.S. dividend tax.” That description is convenient, but not quite right. W-8BEN does not create a tax break. It tells the broker or other withholding agent who you are for U.S. tax purposes and, where appropriate, gives it the documentation needed to apply a treaty rate that already exists under U.S. law.
The most important point: your passport does not, by itself, determine the withholding rate. Your U.S. tax status, treaty residence, type of income, and eligibility under the treaty all matter.
IRS sources rechecked: October 17, 2026. Treaty rates and withholding procedures can change, so material decisions should be checked against current IRS guidance and the treaty itself.
What W-8BEN actually tells your broker
The full name of the form is a mouthful: Certificate of Foreign Status of Beneficial Owner for United States Tax Withholding and Reporting (Individuals).
The name tells you what the IRS is trying to establish.
Your broker needs to know whether the person who owns the income is a U.S. person or a foreign person. If you are foreign, it may also need to know whether you are entitled to a reduced rate under an income-tax treaty.
You normally give W-8BEN to the withholding agent — usually your brokerage, bank, or other payer. You do not normally mail the form to the IRS yourself.
That distinction matters because the broker is the party deciding how much U.S. tax to withhold when the payment is made.
First make sure W-8BEN is actually your form
One of the easiest mistakes is assuming that every non-U.S. citizen should complete W-8BEN.
That is not how the system works.
A non-U.S. citizen can still be a resident alien for U.S. tax purposes. Once that happens, W-8BEN is generally no longer the normal withholding form; a resident alien is generally treated as a U.S. person for this purpose and uses Form W-9 instead.
Likewise, W-8BEN is an individual form. Foreign companies and other entities generally use W-8BEN-E or another form appropriate to their status.
| Situation | Form you will commonly encounter |
|---|---|
| Nonresident alien individual receiving applicable investment income | W-8BEN |
| U.S. citizen or resident alien | W-9 |
| Foreign corporation or other foreign entity | W-8BEN-E or another applicable W-8 form |
| Certain income effectively connected with a U.S. trade or business | W-8ECI may be appropriate |
If you are unsure whether you are a resident or nonresident alien, resolve that question first. Our guide for non-U.S. citizens opening brokerage accounts explains why immigration status and tax residency are not the same thing.
Why the U.S. starts at 30%
For a nonresident alien, certain U.S.-source income that is not effectively connected with a U.S. trade or business falls under the withholding regime commonly associated with FDAP income — fixed, determinable, annual, or periodical income.
Dividends are one of the most familiar examples.
When a U.S. corporation pays a dividend to a nonresident alien, the statutory withholding rate is generally 30% unless the Internal Revenue Code or an applicable income-tax treaty provides something better.
That is why a broker with no valid documentation supporting a lower rate can end up withholding $30 from a $100 dividend.
But “foreign investors pay 30%” is still a poor summary of the law. Different kinds of investment income receive very different treatment.
Qualifying bank-deposit interest, for example, can generally be exempt from U.S. tax for an NRA. Qualifying portfolio interest has its own exemption. Capital gains follow a separate sourcing and tax regime. Retirement distributions have yet another set of rules.
So whenever you see a tax percentage attached to the phrase “foreign investor,” ask one more question:
Thirty percent of what?
The treaty rate follows your tax residence, not your passport
This is where many otherwise good explanations go wrong.
Suppose you are a South Korean citizen. That alone does not automatically give you the benefits of the U.S.–Korea income-tax treaty.
The treaty looks to whether you are a resident of Korea for treaty purposes.
A Korean citizen who has moved permanently to another country and become a treaty resident there may have a completely different U.S. treaty position from a Korean citizen who continues to live and pay tax in Korea.
That is why W-8BEN asks separately about citizenship and treaty residence.
They often match. They do not have to.
For a Korean individual investor, the usual dividend rate is 15% — not 10%
This deserves its own section because it is easy to find the wrong figure online.
The IRS treaty table currently lists two dividend rates for South Korea:
- 15% for general dividends; and
- 10% for dividends that qualify for the treaty’s lower direct-dividend rate.
The second rate is not simply a better rate that any retail investor can choose. It is tied to the treaty’s ownership requirements and is generally relevant to qualifying direct corporate ownership rather than an ordinary individual holding a small portfolio position.
For the typical Korean retail investor holding shares of a U.S. company through a brokerage account, the important number is therefore generally 15%, assuming the investor qualifies as a Korean treaty resident and the treaty benefit is properly documented.
Without an applicable treaty rate: $1,000 dividend × 30% = $300 withheld
Qualifying Korean treaty resident at the general dividend rate: $1,000 × 15% = $150 withheld
That is a $150 difference on a $1,000 dividend — enough to make getting the documentation right worth the effort.
Dividend rates are not the same from one treaty to the next
South Korea is also a useful reminder not to memorize a generic “foreign investor rate.”
The IRS treaty table shows materially different rates across countries.
| Treaty country | General dividend rate | Qualifying direct-dividend rate |
|---|---|---|
| South Korea | 15% | 10% |
| China | 10% | 10% |
| Japan | 10% | 5% |
| India | 25% | 15% |
| Canada | 15% | 5% |
| No applicable treaty | 30% | 30% |
The IRS treaty table is a useful starting point, not a substitute for the treaty itself. Ownership requirements, limitation provisions, income type, and other conditions can affect whether a reduced rate is available.
A $2,400 dividend audit: what a late W-8BEN can cost
Consider a hypothetical Korean treaty resident who owns ordinary U.S. corporate shares through a broker. Assume this individual qualifies for the U.S.–Korea treaty’s general 15% dividend rate for the entire year, that all four payments are eligible U.S.-source ordinary dividends, and that no other tax adjustment applies.
The broker has no sufficient treaty documentation for the first two payments, then begins applying 15% after the investor completes the required W-8BEN documentation. Here is the year-end result.
| Dividend payment | Gross | Withheld | Cash received |
|---|---|---|---|
| Payment 1 — 30% | $600 | $180 | $420 |
| Payment 2 — 30% | $600 | $180 | $420 |
| Payment 3 — 15% | $600 | $90 | $510 |
| Payment 4 — 15% | $600 | $90 | $510 |
| Year total | $2,400 | $540 | $1,860 |
At a 15% treaty rate on all $2,400, the illustrative U.S. tax would be $360 ($2,400 × 15%). The broker withheld $540. The difference is $180 of potential excess withholding — not an automatic refund.
The point: submitting W-8BEN later may change withholding on future dividends, but it does not by itself reverse amounts already withheld. A separate correction or eligible refund claim may be needed.
Method: all amounts are arithmetic illustrations, not returns from a real brokerage account. This assumes the treaty applies to all payments; it does not establish eligibility, refund entitlement, state tax, or tax due in the investor’s country of residence. The 15% Korean portfolio-dividend rate follows Article 12 of the U.S.–Korea treaty.
The form itself is simpler than most tutorials make it look
Many brokers now collect W-8BEN information through an online interview rather than asking you to upload the IRS paper form. The screen may look different, but the broker is still trying to establish the same underlying facts.
The easy parts are your name and basic identity information.
The places worth slowing down are tax residence, your permanent address, tax identification numbers, and the treaty claim.
Your permanent-residence address is not simply whatever address is easiest to enter. The IRS instructions tie it to the country where you claim to be resident for income-tax purposes. A post-office box, a bank’s address, or an address used only for mail is not a substitute for your actual permanent-residence information.
That becomes especially important if you are claiming treaty benefits. The country behind the address and the country whose treaty you are claiming should make sense together.
The tax-ID section creates a different kind of confusion.
Some investors see a box for a U.S. SSN or ITIN and conclude that they cannot invest without one. Others read that an ITIN may not be necessary and conclude that no tax identification number matters at all.
Both conclusions are too broad.
For certain treaty claims involving actively traded securities, an investor may not need to obtain a U.S. ITIN solely to claim the treaty benefit. But the IRS also requires a foreign tax identifying number, or FTIN, in many financial-account situations unless an exception applies.
For a person who is tax-resident in Korea, for example, the relevant foreign tax number is a Korean tax identifier — not a number issued by the IRS.
Think of it this way: “I do not have a U.S. tax ID” and “I do not need to provide any tax-identification information” are two very different statements.
If your jurisdiction does not issue an FTIN to you, or you are not legally required to obtain one under the conditions in the instructions, the form provides a way to indicate that as well.
The point is not to memorize box numbers. It is to make sure the information tells one coherent story about who you are and where you are tax-resident.
W-8BEN field map: what matters before clicking Submit
These are the entries most likely to change the withholding result. A broker may present them in a different order in an online certification flow.
| Paper form | What to establish | Common pitfall |
|---|---|---|
| Line 1–2 | Legal name; country of citizenship. | Treating citizenship as proof of treaty residence. |
| Line 3–4 | Permanent residence; mailing address if different. | Using a mailing-only address as permanent residence. |
| Line 5 | U.S. SSN or ITIN, when required for your claim or circumstances. | Assuming every investor needs a U.S. ITIN — or that none ever does. |
| Line 6a–6b | Foreign tax identification number, or applicable “not legally required” certification. | Leaving it blank without checking the financial-account rules. |
| Line 9 | Country of residence for income-tax treaty purposes, if claiming a treaty. | Selecting the country shown on the passport by default. |
| Line 10 | Special treaty conditions only when the claim requires them. | Copying another investor’s article and 10% rate for ordinary dividends. |
The IRS instructions say Line 10 is generally not required for ordinary treaty interest and dividend claims, apart from additional conditions such as special ownership-based rates. The certification in Part III still matters. Do not put fictional details into a tax form, and follow your broker’s requested documentation process. See IRS W-8BEN line-by-line instructions.
Do you really need to type a treaty article and tax rate into the form?
Not necessarily.
This is another area where online examples can create more work — and more mistakes — than the IRS instructions require.
The treaty section first asks you to identify the country where you claim residence for purposes of the income-tax treaty.
There is also a place for “special rates and conditions.” But the IRS says that this additional explanation is generally not required for ordinary treaty benefits on interest or dividends.
It becomes important when the reduced rate depends on an additional condition that is not already covered by the basic treaty-residence certification.
A good example is a preferential dividend rate based on a specified ownership interest in the company paying the dividend.
That is why copying somebody else’s treaty article, percentage, and explanation from a Reddit post or blog is a poor way to complete the form. Two investors with the same nationality may have different treaty residence, ownership, income, and eligibility.
For a normal retail investor claiming the ordinary portfolio-dividend rate, less improvisation is usually better than more.
How long does W-8BEN stay valid?
You will often hear that W-8BEN “expires every three years.” That is close enough for casual conversation, but the actual rule is slightly different.
In general, the form remains valid from the date it is signed through the last day of the third succeeding calendar year.
So if you sign a W-8BEN on August 18, 2026, it would generally remain valid through December 31, 2029, assuming nothing happens in the meantime that makes the information incorrect.
That last part matters.
You should not wait for the calendar expiration date if your circumstances materially change.
If information on the form becomes incorrect, the IRS generally requires you to notify the withholding agent within 30 days and provide a new W-8BEN or another appropriate form.
Moving to the United States can trigger that issue. So can moving out of the country whose treaty benefits you were claiming. Becoming a U.S. resident alien is another obvious example.
At that point, the problem is not that your old W-8BEN is “too old.” It is that it no longer describes you correctly.
What Form 1042-S tells you at tax time
W-8BEN is what you give the broker.
Form 1042-S is part of the reporting trail that comes back the other way.
Withholding agents use Form 1042-S to report certain U.S.-source income paid to foreign persons and the U.S. tax withheld. U.S.-source dividends paid to an NRA are generally reportable even when a treaty reduces the withholding rate.
For an investor, the form is worth keeping.
It tells you, among other things, how much income was reported and how much U.S. tax was withheld. That information can matter if you need to file a U.S. return, claim credit for withholding, reconcile an incorrect rate, or deal with foreign-tax-credit rules in your country of residence.
If your broker withheld 30% when you believe 15% should have applied, Form 1042-S is one of the first documents to pull up.
Read Form 1042-S before assuming the broker owes you a refund
If your cash distributions do not match the rate you expected, check the underlying records in this order. Brokers may issue more than one Form 1042-S when income or applicable rates differ; do not assume one form covers every dividend you received.
| 1042-S item | Why you check it |
|---|---|
| Box 1 — Income code | Distinguishes the type of income; ordinary corporate dividends are not necessarily reported like interest or other distributions. |
| Box 2 — Gross income | Shows the gross payment amount, before U.S. withholding. |
| Box 3b / 4b — Tax rate | Shows the rate reported for the applicable withholding chapter; do not assume it always equals the effective percentage taken from your cash payment. |
| Box 7a — U.S. federal tax withheld | A key amount to reconcile with the actual withholding; check Box 8 if another withholding agent was involved and Box 9 for certain repayment adjustments. |
For a possible refund, keep the year-end Form 1042-S and the broker’s transaction statements showing the individual dividend payments. An IRS nonresident return claiming tax withheld at source generally requires the applicable Form 1042-S as evidence. IRS Form 1042-S instructions and IRS Form 1040-NR instructions explain the reporting and documentation.
If the broker already withheld 30%, the money may not necessarily be gone
Suppose you were genuinely entitled to a lower treaty rate, but your account was not properly documented and the broker withheld the full 30%.
That does not automatically mean the excess becomes your permanent U.S. tax bill.
Depending on the timing and circumstances, the withholding agent may have procedures available to correct overwithholding. If the issue is not corrected by the payer, an eligible nonresident alien can use the U.S. tax-return process to claim the proper credit or refund — commonly through Form 1040-NR when that return is appropriate.
That is one reason to keep the Form 1042-S rather than treating brokerage withholding as a final statement of your tax liability.
Of course, a refund is not automatic simply because 30% feels too high. You still need to establish that you qualified for the treaty benefit and that your correct U.S. liability was lower than the amount withheld.
Already lost 30%? A four-step correction checklist
Do this before paying someone to file a refund claim — particularly when the potential difference is small.
- Verify that 15% was truly available. Determine whether you were a nonresident alien and a qualifying treaty resident for the relevant payments; check that the dividend income and beneficial owner qualify. The amount of withholding alone does not prove a refund is due.
- Ask the broker what rate was on file on each payment date. Supply or correct W-8BEN through the broker’s established process, and ask whether the withholding agent can use an IRS-compliant reimbursement or set-off procedure for overwithholding. Availability depends on timing, previous reporting, and agent-specific handling; it is not an unconditional right to an instant brokerage refund.
- Collect the paperwork if the broker cannot correct it. Download relevant 1042-S forms, dividend statements, proof of treaty residence, and records of W-8BEN submissions. For eligible nonresident individuals, a Form 1040-NR filing may be the appropriate route to claim overpaid U.S. tax. A U.S. taxpayer ID may be necessary for that filing even if it was not needed merely to claim ordinary dividend withholding treatment.
- Compare possible recovery with effort and costs. In our $2,400 example, the difference is $180 before potential filing costs. Do not assume every $180 is refundable; review the correct U.S. tax liability, any applicable treaty conditions, paperwork, filing deadlines, and residence-country taxes.
Important: A newly accepted W-8BEN does not itself amend a previously issued Form 1042-S, establish your entitlement for earlier payments, or cause the IRS to send a refund automatically. The withholding agent’s correction procedures and the investor’s federal tax-return refund process are separate.
IRS references: Form 1042 adjustment procedures, nonresident returns and refund claims, and Form 1040-NR instructions.
W-8BEN does not make your capital gains tax-free
W-8BEN is principally a withholding and status-certification document. It is not a blanket tax exemption for everything that happens inside your brokerage account.
Capital gains are a good example.
Many securities gains realized by nonresident aliens are not subject to U.S. federal income tax under the general rules, but there are important exceptions.
One of them applies to certain nonresident aliens who are physically present in the United States for 183 days or more during the tax year. In that situation, applicable U.S.-source net capital gains can be subject to a 30% rate or a lower treaty rate.
That 183-day rule is separate from the 183-day calculation used in the Substantial Presence Test.
For students and other people who can remain nonresident aliens while spending long periods physically in the United States, that distinction can matter. Our F-1 student investing guide goes into the tax-home and 183-day problem in more detail.
And W-8BEN says nothing about what your home country will tax
A reduced U.S. withholding rate is only one side of a cross-border investment.
Your country of tax residence can also tax the dividend, interest, or capital gain under its own law. Depending on that country’s rules and the treaty, you may be able to claim some form of foreign-tax credit for U.S. tax already paid.
That is why “the U.S. withheld 15%” and “my total tax rate is 15%” are not the same statement.
W-8BEN deals with the U.S. withholding side. It does not calculate your final worldwide tax bill.
The mistakes worth avoiding
The expensive W-8BEN errors are usually not complicated tax-law mistakes. They are ordinary assumptions made at the wrong point in the process.
Using citizenship as a shortcut for treaty residence. A passport tells the IRS one thing; treaty residence answers a different question.
Picking the lowest rate in a treaty table. The 10% Korean direct-dividend rate, for example, is not simply an alternative to the 15% portfolio rate for an ordinary retail investor.
Assuming no U.S. ITIN means no tax number is needed. Foreign tax-identification requirements can still apply.
Overfilling the treaty section. More text does not make a W-8BEN more valid. For ordinary portfolio dividends, the IRS generally does not require the special-conditions field unless an additional treaty condition has to be established.
Leaving an old form on file after your tax status changes. A form can still be within its normal validity period and already be wrong.
Before you submit or renew W-8BEN
- Make sure you are still a nonresident alien for U.S. tax purposes.
- Confirm the country where you are actually resident for treaty purposes.
- Look up the rate for the specific type of income you expect to receive.
- Do not use a direct-dividend rate unless you actually satisfy its ownership requirements.
- Enter your real permanent-residence information.
- Check whether a U.S. TIN, foreign TIN, or an applicable exception is relevant to your account.
- Keep the Form 1042-S and other annual brokerage tax records you receive.
- Update your documentation promptly if you move or your U.S. tax status changes.
Frequently asked questions
Does W-8BEN automatically reduce U.S. dividend withholding to 15%?
No. Fifteen percent is common under a number of treaties, but W-8BEN does not create a universal 15% rate. The applicable rate depends on the treaty, your treaty residence, the income involved, and whether you qualify for the benefit.
What rate usually applies to a Korean retail investor receiving U.S. dividends?
For a qualifying South Korean treaty resident, the IRS treaty table currently lists a 15% general dividend rate. The 10% rate is the qualifying direct-dividend rate and should not be assumed to apply to a normal minority portfolio investment.
Do I send W-8BEN to the IRS?
Normally, no. You provide it to the withholding agent or payer requesting it, such as your broker or financial institution.
Do I need a U.S. ITIN just to receive the treaty rate on U.S. stocks?
Not necessarily. IRS rules include exceptions from the U.S.-TIN requirement for certain treaty benefits involving actively traded securities. But that does not eliminate foreign-TIN requirements that may apply to your financial account.
Why does my broker ask for a foreign tax number?
For certain financial accounts held at a U.S. office of a financial institution, the W-8BEN rules generally require the foreign tax identifying number issued by the investor’s jurisdiction of tax residence unless an exception applies.
Do I need to fill in the “special rates and conditions” section for ordinary stock dividends?
Usually not merely because you are claiming an ordinary treaty dividend rate. The IRS says that section is generally not applicable to normal treaty benefits for interest or dividends unless an additional condition — such as a preferential rate based on ownership — must be established.
How long is W-8BEN valid?
Under the general rule, it remains valid from the date it is signed through the end of the third succeeding calendar year, unless a change in circumstances makes the form incorrect sooner.
Can I get back tax that was withheld at the wrong rate?
Potentially. If you were entitled to a lower U.S. tax rate and excess tax was withheld, the amount may be recoverable through the applicable withholding-agent correction procedure or U.S. tax-return process. Form 1042-S is important evidence of the income and withholding reported in your name.
Where to go next
If you are not certain whether W-8BEN is the right form for you, start with Can a Non-US Citizen Open a Brokerage Account?.
If you need an account provider that actually serves your country of residence, continue with our Brokerages for Non-Residents and Visa Holders.
And if you want to see why U.S. Treasury interest and bank interest can receive very different treatment from corporate dividends, read Do Foreigners Pay U.S. Tax on Treasury Bonds and CDs?.
Free KoruVest tool
Not sure whether a broker accepts your residency and tax-ID situation?
Use the Brokerage Readiness Checker to identify application requirements you should verify. It does not determine your treaty eligibility or calculate your tax refund.
📚 Primary sources
- IRS — About Form W-8BEN
- IRS — Instructions for Form W-8BEN
- IRS — Tax Treaty Tables
- IRS — Table 1: Tax Rates on Income Other Than Personal Service Income
- IRS — U.S.–Republic of Korea Income Tax Convention
- IRS — U.S.-Source Income Paid to Nonresident Aliens
- IRS Publication 515 — Withholding of Tax on Nonresident Aliens and Foreign Entities
- IRS — Instructions for Form 1042-S
- IRS — Form 1042 correction and overwithholding procedures
- IRS — Form 1040-NR instructions, proof of withholding and refund claims
- IRS — Taxation of nonresident aliens and refund filing requirements
- IRS — Capital Gains and the Separate 183-Day Rule
KoruVest cross-checked these IRS sources on October 17, 2026. IRS treaty tables are summaries; the treaty itself and the investor’s individual facts determine whether a reduced rate is available.
✍️ About the Author
David Han is the lead author of KoruVest, covering beginner investing, U.S. financial accounts, taxes, and cross-border financial issues for international investors.
KoruVest articles are researched using official and authoritative sources and follow our standards for source review, fact checking, updates, and editorial independence.
⚠️ Disclaimer
Educational only. This article provides general information and is not personalized tax, legal, financial, or investment advice.
Cross-border tax treatment is fact-specific. Tax residence, treaty eligibility, beneficial ownership, income type, and changes in status can alter the result.
For a material withholding or refund issue, consult an appropriately qualified cross-border tax professional. See our full Disclaimer.
Published: July 20, 2026 · Updated: October 17, 2026