October 15, 2026 has passed. That was the usual automatic-extended filing deadline for an FBAR reporting foreign accounts held during calendar year 2025. If you believe you were required to file and did not, the relevant question today is not whether you can request another routine extension; it is how to determine your obligation, check any applicable special relief, and use the appropriate late-filing procedure.
The next reporting cycle is different: foreign accounts held during calendar year 2026 are generally reported by April 15, 2027, with an automatic extension to October 15, 2027. Those dates refer to a different account year—not an extension of the missed 2025 report.
FBAR is FinCEN Form 114, a separate report of certain financial accounts located outside the United States. Filing it does not itself calculate or collect income tax, and electronic filing is free. However, an FBAR obligation can exist alongside a separate duty to report and pay tax on foreign-account income.
The reason visa holders miss it is that the obligation does not always arrive with a notice. It can begin when a person’s U.S. residency classification changes, even though the account back home has existed for years.
If you hold a green card, work in H-1B status, or have spent enough qualifying time in the United States for your F-1 days to count, start with the residency test rather than the visa label.
Current deadline status · Checked October 17, 2026
For a typical individual filer, the automatic-extended 2025 FBAR deadline has passed. Disaster relief and certain special exceptions can change the applicable deadline. Verify the facts before deciding a filing is late. Check the IRS FBAR filing guide →
Mainstream FBAR guidance is written for a different reader
Search for FBAR guidance and most of what you find is addressed to U.S. citizens living abroad. Expat tax firms, accounting practices, guides written for Americans in London or Singapore.
Visa holders face the mirror-image problem. They may live inside the United States while the accounts that create the reporting question remain back home. The residency analysis runs in the opposite direction, the accounts are in the country of origin rather than the country of residence, and the moment the obligation begins is usually a change in status rather than a move.
Content aimed specifically at H-1B holders does exist, and some of it is good. What is harder to find is a clear treatment of the transition — how someone moves from having no obligation to having one, without their money changing at all.
For visa holders, the filing trigger is U.S.-person status, not the visa label
An H-1B visa does not automatically create an FBAR obligation, and an F-1 visa does not automatically prevent one.
The IRS states that a U.S. person — including a citizen, a resident, and various entities — must file an FBAR to report a financial interest in or signature or other authority over at least one financial account located outside the United States, if the aggregate value of those accounts exceeded $10,000 at any time during the calendar year reported.
For a non-U.S. citizen, the operative question is generally whether the individual is a U.S. resident under the residency rules incorporated into the FBAR regulations, which include the green card test and the substantial presence test. Nonresident aliens are generally not required to file.
Two FBAR-specific twists are worth knowing, because both cut against intuition.
A treaty position does not erase FBAR status. Someone who is a U.S. resident under the residency rules but claims treatment as a nonresident for income-tax purposes under a tax treaty generally remains a U.S. person for FBAR purposes. The income-tax result and the FBAR result can diverge.
Electing to file jointly with a U.S. spouse does not create FBAR residency. A nonresident alien who elects under Internal Revenue Code section 6013(g) or 6013(h) to be treated as a resident in order to file a joint return with a U.S. spouse is treated as a resident for income-tax purposes. That election is generally disregarded in determining FBAR residency. Marriage to a U.S. citizen, on its own, does not make you a U.S. person for this filing.
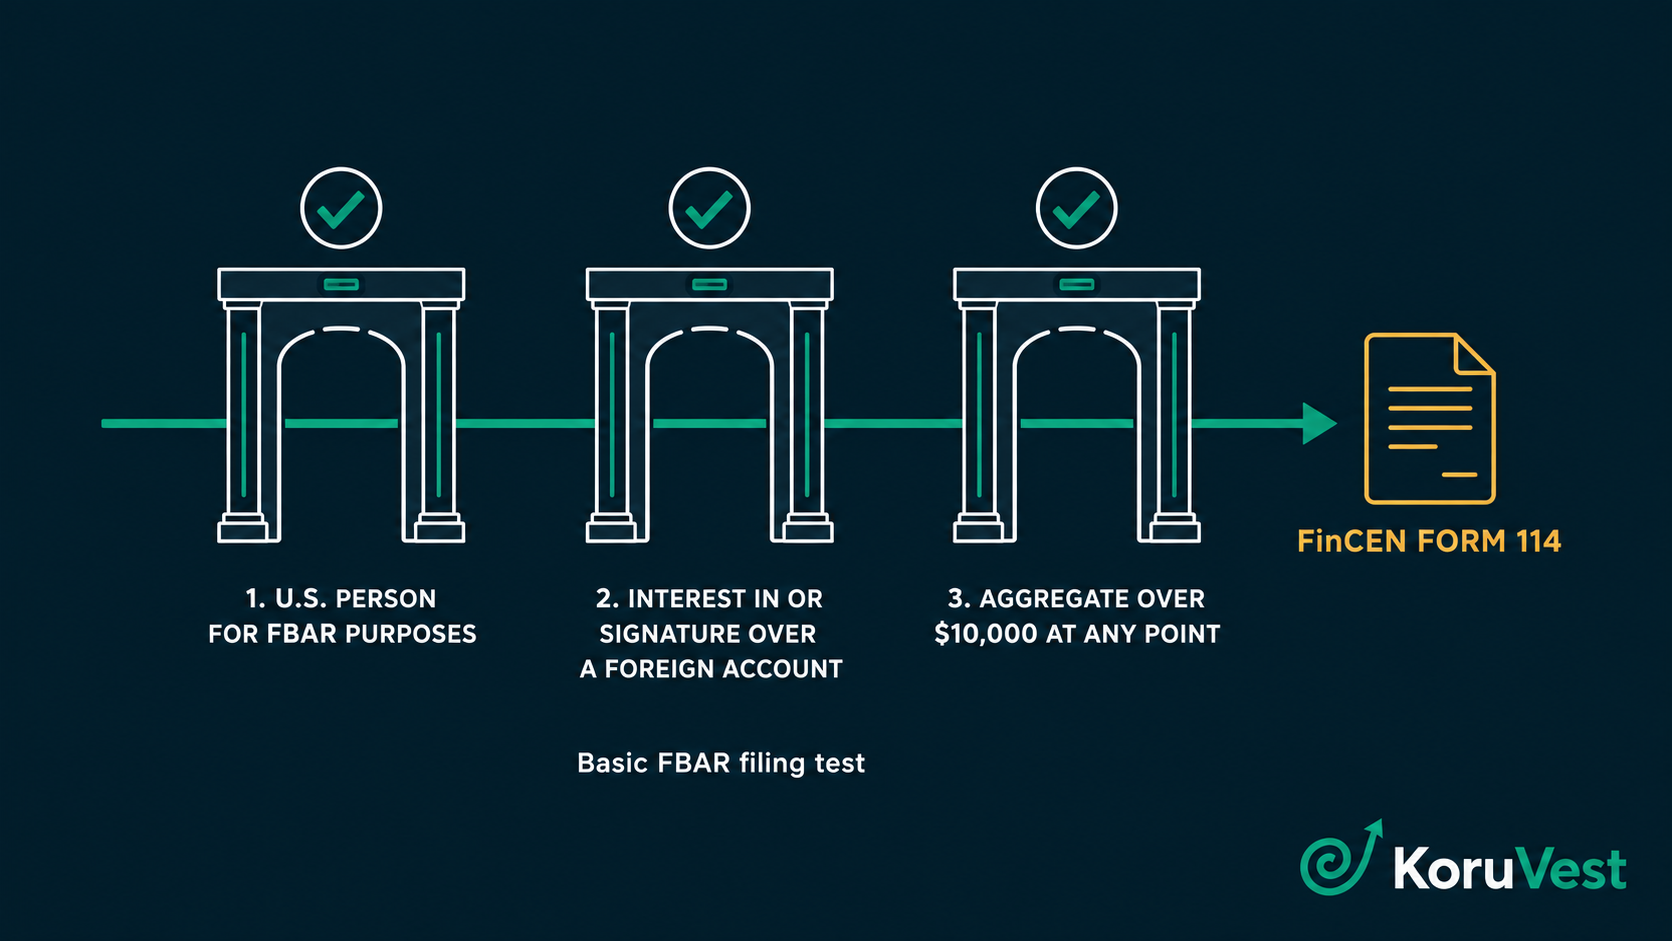
The basic test has three parts: you are a U.S. person for FBAR purposes, you have a financial interest in or signature authority over at least one foreign financial account, and the combined value of those accounts exceeded $10,000 at any point in the calendar year. Statutory exclusions can remove particular accounts from the calculation, which is covered below.
For an F-1 student, the change is in the residency test, not in the accounts
This is the transition that catches people, and it is worth stating precisely rather than simply.
Students in F, J, M, or Q status are generally treated as exempt individuals for the substantial presence test, which means their days of presence in the United States are not counted. The IRS applies this for a limited period — generally the first five calendar years of presence as a student.
What happens after that is not automatic residency. Once the exempt period ends, the days begin to count, and the person becomes a resident alien only if the substantial presence test is then actually satisfied. In limited circumstances, continued exempt-individual treatment can be claimed beyond five years where the specific requirements are met.
So the accurate version is this: after the exempt period, a student who satisfies the substantial presence test generally becomes a resident alien — and a reporting obligation can appear for the first time.
The savings account in Seoul or Mumbai did not change. The residency test did.
Similar discontinuities appear at other transitions — F-1 to H-1B, a change of status partway through a year, receipt of a green card. Each can alter residency, and residency is what drives this filing. We covered the five-year exempt window in more detail in our guide to investing on an F-1 visa.
Where residency begins partway through a calendar year, the interaction between the residency start date and a calendar-year filing is genuinely intricate. If your status changed during the year in question, that fact pattern deserves a professional’s attention rather than a general article’s.
The $10,000 threshold is not what most people assume it is
Two features of the threshold catch people, and both run toward more filing rather than less.
The first is that it is aggregate, not per account. For the threshold test, determine each reportable foreign account’s maximum annual value, convert it as required, and add those maxima. The comparison is between that total and $10,000 — not between one account and $10,000. FinCEN’s instructions do not require each account to reach its annual peak on the same date.
The second is that annual maximum values matter, not just December balances. An account can briefly reach a high balance and finish the year much lower. A December statement showing $3,000 does not settle the question. For a precise calculation, follow FinCEN’s maximum account value instructions.
This is why a lump-sum transfer is such a common trigger. A parent wires a year of tuition into a student’s home-country account in September; the money leaves for the university in October. The account spent six weeks above the threshold.
Three real-life-style cases: who files, and which year?
These are illustrative fact patterns, not individual filing determinations. Each assumes the accounts are otherwise reportable and that no special exception or relief applies. A visa category alone is never enough to settle the U.S.-person question.
| Illustrative person | Account facts | What to check |
|---|---|---|
| F-1 student still an NRA for FBAR purposes | Foreign savings account peaks at $18,000. | If not a U.S. person for FBAR purposes, a high balance alone generally does not create an FBAR filing duty. Verify residency and any prior presence. |
| H-1B worker who is a U.S. resident | Korean bank peaks at $7,000 and an Indian brokerage peaks at $5,000 in the same year. | Annual maxima total $12,000, exceeding $10,000. Both reportable accounts generally belong on the FBAR, even if the peaks occurred on different dates. |
| Resident visa holder who missed the 2025 FBAR | Account exceeded $10,000 in 2025; nothing was filed by October 15, 2026. | Check for special relief, whether all relevant income was reported, any IRS contact or examination, and the appropriate late-filing explanation. Do not simply wait for the 2026 FBAR cycle. |
Method: $7,000 + $5,000 = $12,000 in the example; figures assume required U.S.-dollar conversion has already been made and exclude foreign-exchange changes. This is an illustration of the threshold, not evidence of actual user cases. Source: FinCEN’s maximum-value guidance.
Crossing the threshold once brings the small accounts in too
The $10,000 test decides whether you file. It does not decide what you report.
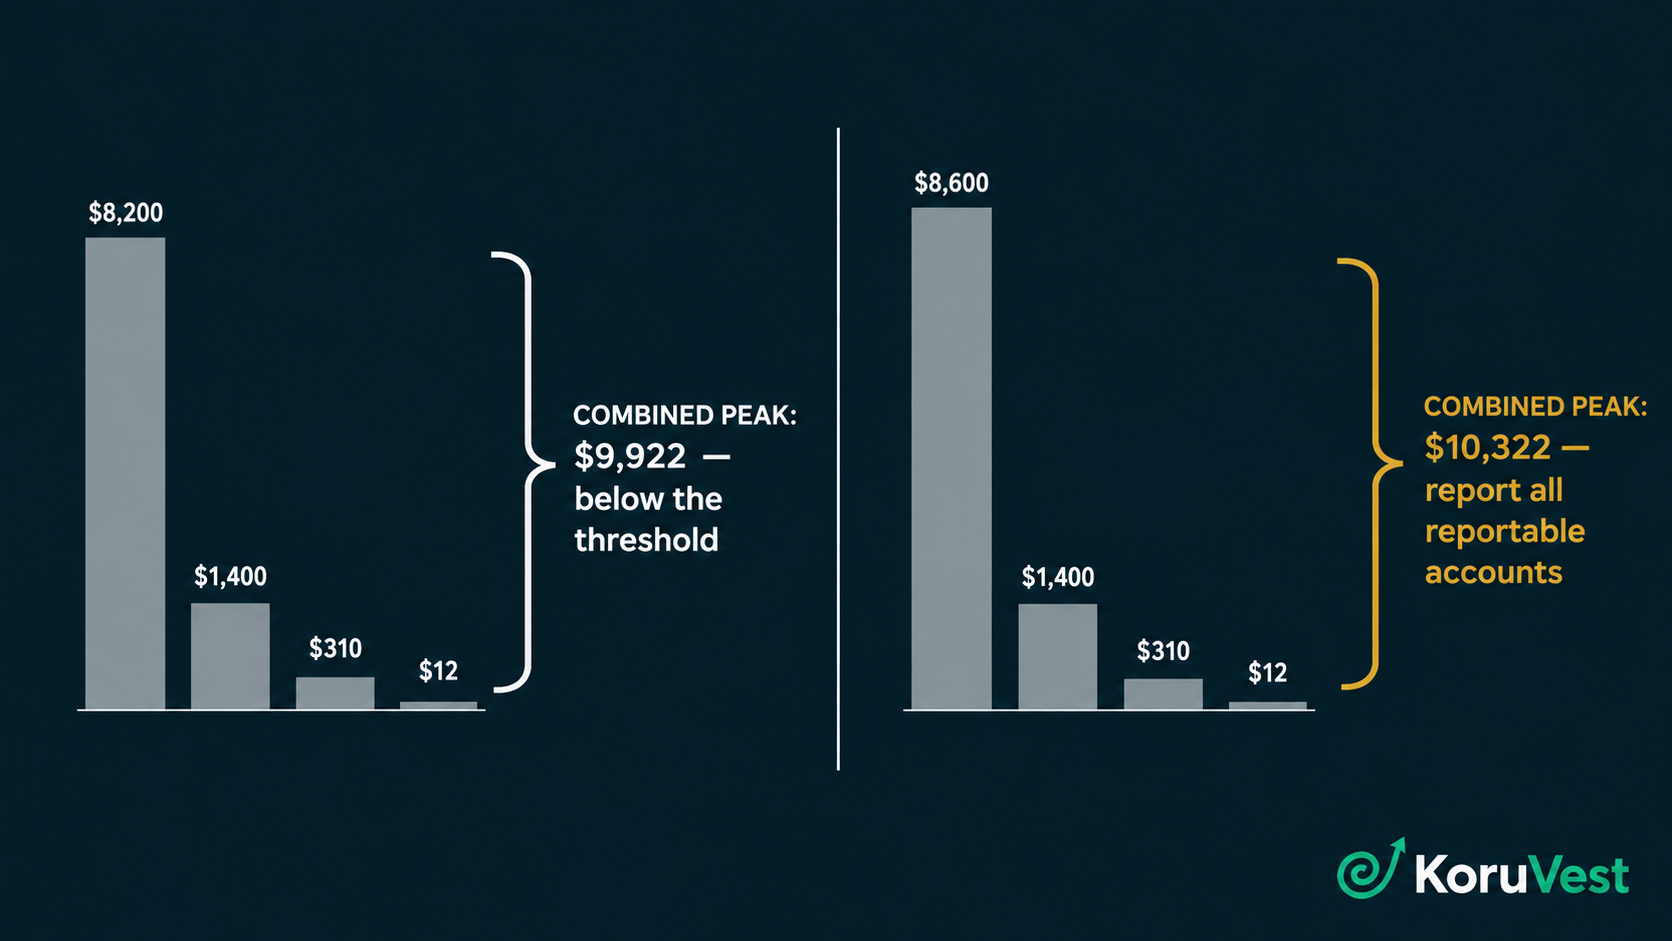
Once the combined total is exceeded, the filing covers every reportable foreign financial account you held during the year — including a dormant account holding the equivalent of twelve dollars, and including accounts that were closed at some point during the year.
Joint accounts are counted at full value rather than at your share. If your name is on a family account with a parent or sibling, the whole balance enters the aggregate calculation.
A common and avoidable error follows from this: filing correctly for the large account and omitting three small ones, on the reasonable-sounding logic that each was below the threshold. The threshold was never about individual accounts.
Filing a tax return does not satisfy this, and it does not go to the IRS
The FBAR is administered by the Financial Crimes Enforcement Network, a bureau of the U.S. Treasury Department, and it is filed electronically through FinCEN’s BSA E-Filing System. It is not attached to Form 1040.
That structural fact explains a large share of missed filings. Someone uses a tax preparation service, files an accurate return, and reasonably assumes the year’s obligations are complete. The FBAR is a separate filing to a separate agency, and unless it was specifically raised, it may not have been addressed.
A related assumption fails for the same reason: the FBAR is independent of whether you owe tax. The IRS states that whether the account produced taxable income has no effect on whether it is a foreign financial account for FBAR purposes. An account earning nothing, in a year you owed nothing, can still be reportable.
Some accounts are excluded, and one you might expect to report is not foreign
The IRS lists specific exclusions. Accounts held in an individual retirement account of which you are the owner or beneficiary, accounts held in a retirement plan of which you are a participant or beneficiary, and accounts maintained on a U.S. military banking facility do not need to be reported.
There is also a location point that works in your favor: an account at a U.S. branch of a foreign bank is generally treated as domestic. A checking account opened at the New York branch of a Korean or Indian bank is generally not a foreign financial account for this purpose. What matters is where the account is located, not the nationality of the institution’s parent.
Foreign retirement arrangements are less clear-cut than the exclusion list suggests at a glance. The exclusions are framed around U.S.-style IRAs and retirement plans, and whether a particular home-country pension or provident arrangement falls inside or outside them depends on its structure. Practitioners routinely include such arrangements in the initial account inventory precisely because the answer is not obvious. If you hold one, treat it as a question rather than an assumption.
Digital assets require a separate check. Under FinCEN Notice 2020-2, a foreign account holding only virtual currency is not currently treated as a reportable FBAR account. If the account also holds assets that are independently reportable under the FBAR regulations, the result can differ. FinCEN has stated that it intends to amend the rules to address virtual currency, so this is an area where current guidance should be checked before filing rather than recalled from an earlier year.
Signature authority counts even when none of the money is yours
The obligation is not limited to accounts you own.
Having signature or other authority over a foreign account — the ability to direct the disposition of its assets — can create a filing obligation on its own, with no financial interest whatsoever.
For visa holders this appears in two recurring situations. One is a family account back home, where a parent adds you as a signatory for convenience. The other is employment, where an employee or officer holds authority over a foreign company account.
Neither situation involves your money. Both can involve your filing.
FBAR filing calendar: the missed 2025 report versus the upcoming 2026 report
FBAR reporting is based on the calendar year in which you held the foreign accounts, not the year when you file the report. A normal FBAR is due April 15 of the following year, with an automatic extension to October 15; no separate request for the automatic extension is required.
| Account year | Regular due date | Usual automatic extension | As of Oct. 17, 2026 |
|---|---|---|---|
| 2025 | April 15, 2026 | October 15, 2026 | Passed for ordinary filers |
| 2026 | April 15, 2027 | October 15, 2027 | Current reporting year; upcoming deadlines |
The dates above are the general rule. Certain disaster-affected taxpayers and narrow categories of financial professionals may qualify for other deadlines; see the IRS and FinCEN notices applicable to your situation. A special deadline is not something to assume merely because you missed the ordinary filing date.
Gather the institution’s name and address, account number and type, and maximum account value for the relevant year. Convert non-U.S.-dollar maximum values following FinCEN’s instructions using the U.S. Treasury’s last-day-of-year reporting rate when available. Historic statements may take time to retrieve.
Missed October 15, 2026? First separate a late FBAR from unreported income
If you were required to file for 2025 but did not, there is generally no second routine extension beyond October 15. The IRS advises people who have not been contacted about a late FBAR and are not under relevant examination or investigation to file delinquent FBARs as soon as possible to limit potential penalties. FinCEN’s e-filing workflow requires a reason for a late submission, including an “other” explanation when appropriate.
- Verify that an FBAR was required. Recheck whether you were a U.S. person for FBAR purposes in 2025, including student exempt-day rules, residency-start questions and applicable exclusions. Confirm the highest values of every potentially reportable foreign account.
- Check for applicable relief. Review any federal disaster-related deadline extension or special FinCEN rule for your facts. A general hardship is not automatically an extension.
- Determine whether foreign-account income was also omitted from your U.S. tax filings. If your income returns are correct and your issue is only a late FBAR, one set of procedures may apply. If tax returns omitted income, or there were other reporting errors, a different compliance route may be necessary.
- Check your contact and examination status. The available procedures can differ if the IRS has contacted you or initiated an examination or investigation. If willfulness or multiple missed years is a concern, seek professional guidance before choosing a route.
- File through the appropriate process and keep records. Use the official FinCEN BSA E-Filing System when appropriate; include the truthful late-filing explanation requested by FinCEN and retain account records and the filing confirmation.
Important: A late FBAR is not automatically penalty-free, and filing it does not correct an omitted federal income-tax return. The IRS has distinct eligibility rules for its streamlined offshore compliance procedures. Do not treat those procedures as a universal shortcut or assume a 5% penalty always applies.
Primary instructions: IRS — FBAR filing and delinquency, FinCEN — Filing Late, and IRS — Streamlined Filing Compliance Procedures.
What the penalties look like, and what the Supreme Court changed
FBAR penalties are severe on paper, which is worth stating plainly rather than softening.
In the eCFR table checked October 17, 2026, the listed inflation-adjusted civil maximums for penalties assessed on or after January 17, 2025 are $16,536 for a non-willful violation, and the greater of $165,353 or 50% of the account balance for a willful violation; criminal exposure may also arise in willful cases. These are maximums under the cited rules, not automatic assessments, and later annual inflation adjustments may change the figures.
The 2023 Supreme Court decision in Bittner v. United States changed the arithmetic for non-willful violations. The Court held that the non-willful penalty applies on a per-report basis — that is, per annual FBAR — rather than per unreported account. Before that decision, the government’s position had been per account, which produced a very different figure for someone with several accounts across several years.
Two points of perspective belong beside the numbers. These are statutory maximums rather than typical outcomes, and the distinction between willful and non-willful conduct does substantial work in practice. None of that is a reason to be casual. It is a reason not to freeze, which is the more common failure.
If you are behind, there are defined procedures
Discovering a missed obligation covering several years is unsettling, and the instinct to do nothing is understandable and usually the worst available option.
The IRS’s delinquent-FBAR guidance advises people who have not been contacted by the IRS and who are not under an examination or investigation to file required late FBARs as soon as possible; FinCEN asks for a reason when a report is filed late. The new five-step checklist above explains why reviewing other tax omissions and special relief comes before choosing a compliance path.
Where income associated with the accounts was not properly reported and the conduct was non-willful, the Streamlined Filing Compliance Procedures may apply. The domestic version carries a miscellaneous offshore penalty of 5%. That 5% is not calculated on the FBAR accounts alone: under the IRS’s description, the year-end aggregate balance or value of the foreign financial assets subject to the penalty is determined for each year in the covered period, and the penalty applies to the highest of those annual figures. The asset scope can be broader than the accounts on an FBAR.
Willful conduct falls under a separate voluntary disclosure framework.
Two things determine which path fits: the willfulness question, and whether you come forward before the IRS contacts you. Both are reasons this is the point in the article where consulting someone experienced in international reporting is the actual answer rather than a disclaimer.
The FBAR and Form 8938 are two different filings
These are routinely confused, and filing one does not satisfy the other. Many people with foreign assets must file both.
| FBAR (FinCEN Form 114) | Form 8938 (FATCA) | |
|---|---|---|
| Filed with | FinCEN, via BSA E-Filing System | IRS, attached to your tax return |
| Threshold | $10,000 aggregate, any point in the year | Higher, and varies by filing status and residence |
| Covers | Foreign financial accounts | A broader range of specified foreign financial assets |
| Deadline | April 15, automatic extension to October 15 | Follows your tax return deadline |
| Cost to file | None | Part of your return |
Form 8938 thresholds depend on filing status and whether you live in the United States. Confirm the figures applicable to your situation with the IRS comparison of the two requirements.
Records matter more than the form. Keep your filing confirmation and the underlying account records. The filing itself is short; reconstructing years-old overseas balances is not.
Frequently asked questions
Is the October 15, 2026 deadline still open?
No, not for an ordinary filer reporting 2025 accounts as of October 17, 2026. Certain special relief rules can change the deadline for particular people. If you were required to file and missed the date, review the late-filing steps above rather than treating the next year’s deadline as an extension.
When is the FBAR for calendar year 2026 due?
The general due date is April 15, 2027, with an automatic extension to October 15, 2027. This report covers accounts held during 2026, not the 2025 accounts that were ordinarily reported in 2026.
Do the two foreign accounts have to exceed $10,000 on the same day?
Not under FinCEN’s account-maximum reporting method. Determine the maximum annual value of each reportable account and add those values for the aggregate test. In the example above, $7,000 plus $5,000 exceeds $10,000 even if the two accounts peaked in different months.
Do F-1 students have to file an FBAR?
Generally not while they remain nonresident aliens. Students in F status are typically treated as exempt individuals for the substantial presence test, generally for their first five calendar years, and nonresident aliens are generally not required to file. After the exempt period, a student who then satisfies the substantial presence test generally becomes a resident alien, and the obligation can apply.
Do H-1B workers have to file an FBAR?
If you are a U.S. resident under the residency rules that apply to the FBAR, the same requirements apply as to a citizen. If your foreign accounts exceeded $10,000 in aggregate at any point in the calendar year, the filing requirement generally applies. The visa category itself is not the test.
My account back home has less than $10,000. Do I still need to file?
Possibly. The threshold is the combined highest balance of all your foreign accounts, not the balance of any single one. Add each account’s peak value. If the total crossed $10,000 at any point in the year, the requirement generally applies — and then all reportable accounts are included, even small ones.
I already filed my tax return. Isn’t that enough?
No. The FBAR is filed with FinCEN, a Treasury bureau, through a separate electronic system. It is not part of Form 1040 and is not sent to the IRS. An accurate tax return does not satisfy the FBAR requirement.
I have no U.S. income and owe no tax. Does this still apply?
Yes, if the conditions are met. The IRS states that whether the account produced taxable income has no effect on whether it is a foreign financial account for FBAR purposes.
I filed jointly with my U.S. citizen spouse. Am I a U.S. person for FBAR purposes?
Not necessarily. An election under Internal Revenue Code section 6013(g) or 6013(h) to be treated as a resident for income-tax purposes is generally disregarded in determining FBAR residency. You would need to be a U.S. resident under the residency rules that apply to the FBAR — for example, by meeting the substantial presence test independently.
Do I report cryptocurrency held on a foreign exchange?
Under FinCEN Notice 2020-2, a foreign account holding only virtual currency is not currently treated as a reportable FBAR account. If the same account also holds assets that are independently reportable, the analysis changes. FinCEN has said it intends to amend the rules, so check current guidance before filing.
Is an account at a U.S. branch of a foreign bank reportable?
Generally no. What matters is where the account is located rather than the nationality of the bank. An account at a U.S. branch is ordinarily treated as domestic for this purpose.
I missed prior years. What should I do?
Do not ignore it. The IRS instructs those who have not been contacted about a late FBAR, and who are not under examination or investigation, to file the delinquent report as soon as possible with a statement explaining the delay. Where income was not properly reported, the Streamlined Filing Compliance Procedures may apply for non-willful conduct. Choosing among the available paths depends on a willfulness assessment that warrants professional advice.
Where to go next
If you are unsure whether you are a nonresident alien or a resident alien, that determination drives this and much else — start with the residency tests explained in our brokerage account guide.
If you are on an F-1 visa, our investing guide for F-1 students covers the exempt-individual window in more detail.
If you are planning to leave the United States, reporting is one of several questions that change on departure — see what happens to your U.S. accounts when you leave.
And if withholding on your U.S. investment income is what brought you here, the W-8BEN and the 30% rule is the companion piece to this one.
📚 Primary sources
- IRS — Report of Foreign Bank and Financial Accounts (FBAR)
- FinCEN — Report Foreign Bank and Financial Accounts
- FinCEN Notice 2020-2 — FBAR Filing Requirement for Virtual Currency
- Supreme Court of the United States — Bittner v. United States (2023)
- eCFR — 31 CFR 1010.821, Penalty Adjustment and Table
- IRS — Publication 519, U.S. Tax Guide for Aliens
- IRS — Substantial Presence Test
- IRS — Exempt Individual: Who Is a Student
- IRS — Comparison of Form 8938 and FBAR Requirements
- IRS — Streamlined Filing Compliance Procedures
- U.S. Treasury — Reporting Rates of Exchange
- FinCEN — Reporting Maximum Account Value
- FinCEN — Filing Late
- IRS — FBAR: Who Must File, When, and Late Reports
Penalty maximums are subject to inflation adjustment, and deadlines, exclusions, and virtual-asset guidance can change. Confirm current rules at irs.gov and fincen.gov before filing.
✍️ About the Author
David Han is the lead author of KoruVest, covering beginner investing, U.S. financial accounts, taxes, and cross-border financial issues for international investors.
KoruVest articles are researched using official and authoritative sources and follow our standards for source review, fact checking, updates, and editorial independence.
⚠️ Disclaimer
Educational only. This article provides general information and is not personalized tax, legal, or immigration advice. We are not tax professionals or attorneys.
Individual facts control. Whether you are a U.S. person for FBAR purposes, whether a particular account is reportable, and how a mid-year change in residency affects a calendar-year filing all depend on your specific circumstances.
Delinquent filings need advice. If you have missed prior-year filings, the choice among available procedures depends on a willfulness assessment. Speak with a professional experienced in international reporting before filing.
Verify current rules. Penalty maximums, thresholds, and guidance change over time. See our full Disclaimer.
Published: August 24, 2026 · Last reviewed and updated: October 17, 2026